
What Does a $100K Investment in a Flexible Workspace Operator Actually Buy You?
A walkthrough of the Pacific Workplaces Fund A waterfall — what investors get, and why the structure matters.
If you've ever looked at a real estate private placement memo, you know they're written by lawyers, for lawyers. The phrase "100% to the Members pro rata to their respective Capital Contributions, until the cumulative non-compounded Preferred Return shall have been met" is doing a lot of heavy lifting in those documents, and most accredited investors I talk to are too polite to ask what any of it means.
Let's actually answer that question — using Pacific Workplaces' Fund A as a working example.
Note: This is an educational walkthrough of how the waterfall works in our offering. It is not an offer to invest, not a solicitation, and definitely not a substitute for the PPM, which will be made available to accredited investors who qualify. Please read the actual deal documents, talk to your advisor, and form your own view.
With that out of the way, here's how a $100,000 investment moves through the structure.
First: the big picture
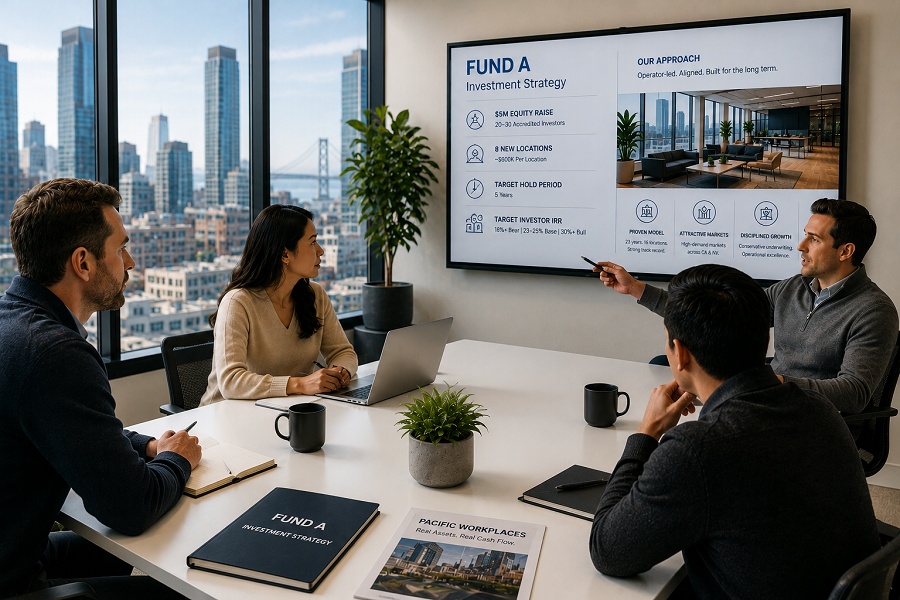
Pacific Workplaces Fund A is a $5 million equity raise from 20–30 accredited investors. The proceeds fund the expansion of 8 new Pacific Workplaces locations, modeled on our 16-location existing portfolio and the recent successful expansion at 315 Montgomery.
Investors are passive limited partners. They get common equity in the new management company, which collects operating cash flow from the 8 new locations and ultimately participates in any exit. The hold period is targeted at 5 years.
Investor returns are governed by a 3-tier waterfall — meaning the cash that comes out of the locations gets divided between investors and the manager in a specific order, based on how well the portfolio performs.
The waterfall, in plain English
Imagine the cash distributions from the 8 locations as water flowing down a series of buckets. Each bucket has to fill before water spills over into the next one. Here's the structure:
Tier 1: 100% to investors until 10% cumulative cash-on-cash.
The first bucket says: investors get every dollar of distributions until they've received a 10% cumulative non-compounded cash-on-cash return on their contributed capital. The word "cumulative" is doing important work here — if year one is lean and you only get 6%, you carry the missing 4% forward. The manager gets nothing until the 10% hurdle is satisfied across the life of the fund.
On a $100K investment, this means investors are first in line for the first $10,000/year of distributions (on average, across the hold).
Tier 2: 83/17 between 10% and 25% cumulative.
Once the 10% preferred return is satisfied, the next bucket is shared between investors and the manager — 83% to investors, 17% to the manager. This continues until the cumulative cash-on-cash return reaches 25%.
This is the "if the deal performs well, we share in the upside" tier. The manager starts earning meaningful carry, but the investors still receive the lion's share.
Tier 3: 60/40 above 25% cumulative.
If the deal performs above a 25% cumulative cash-on-cash return — the bull case — the third tier kicks in, with 60% to investors and 40% to the manager.
This is the alignment tier. If the manager is delivering 25%+ returns, the manager has earned a much larger share of the marginal dollar.
A 1.5% annual management fee sits above all of this
This is paid first, off the top, and covers the operational cost of running the fund (reporting, K-1s, investor communications, compliance).
This is a relatively standard fee for an operator-led real estate fund. Larger institutional funds typically charge 2%+. Smaller, retail-targeted real estate funds often charge 2.5%+. We landed at 1.5% because the operating company already exists, the marginal overhead is modest, and the alignment is in the carry, not the fee.
At exit: capital comes back first
One thing that's distinct about how we structured Fund A: at any exit event (sale of one or more locations, sale of the management company, refinance), the first tier of the exit waterfall is a 100% return-of-capital tier. Investors get their $100K back before any of the operating-cash-flow waterfall splits apply to the exit proceeds.
Only after every dollar of contributed capital is returned does the manager start receiving carry on the exit. This is a feature, not a quirk — it materially derisks the bear case for investors and is one of the changes we made in the final structure.
So what does a $100K investment actually look like?
Here's the rough shape across the three scenarios in our financial model:
- Bear case: Around an 18%+ target investor IRR over the 5-year hold. This assumes some locations underperform, the exit is at the low end of comparables, and the operating environment is harder than expected.
- Base case: Around 23–25% target investor IRR. This assumes the 8 new locations perform in line with our existing portfolio's historical economics, with a clean exit at comparable market multiples.
- Bull case: Around 30%+ target investor IRR. This assumes the 8 new locations outperform, the AI/flex-space demand wave continues, and the exit multiple expands.
Those are targets, not guarantees. Actual results may differ materially. Please read the risk factors in the PPM.
Why this structure matters
There are a few things I want to flag about this waterfall design, because they're not standard and they reflect what we've learned from 23 years of operating in this category.
Cumulative cash-on-cash, not IRR-based hurdles.
Most real estate funds use an IRR-based preferred return — "investors get an 8% IRR before the manager earns carry." The problem with IRR-based hurdles in coworking is that IRR is heavily sensitive to the timing and size of the exit. Coworking exits are lumpy and rare. There aren't many buyers for a 16-location regional coworking portfolio — the strategic acquirers are a short list (Industrious/CBRE, IWG, a handful of private equity platforms).
If the manager is compensated only on IRR, and the portfolio is genuinely valuable but doesn't have a clean exit window, the manager gets squeezed even if they ran a great business. Conversely, if the right exit happens at the right moment, IRR-based hurdles can shift a lot of value to the manager that doesn't reflect actual operating performance.
Cash-on-cash hurdles avoid both of those distortions. Investors are paid out based on what actually came out of the business each year, plus their share of the exit. It's a cleaner alignment with how this asset class actually works.
100% return of capital at exit before manager carry.
This is non-standard. Many funds blend the exit waterfall with the operating waterfall, which can mean the manager earns carry on the exit even if investors haven't recovered their capital. We took the other side of that — capital comes back first.
The carry split is a real carry split.
The 17% in Tier 2 and 40% in Tier 3 to the manager isn't paid to a passive sponsor. It's paid to the operating team — myself, Laurent Dhollande (CEO of PAC), and Scott Chambers — in defined percentages. We are operators, not financial sponsors. Our compensation is structurally tied to the performance of the underlying business.
Takeaways for investors
- Read the waterfall, not just the headline return number. Two funds with the same "25% target IRR" can have wildly different investor experiences depending on how the tiers are designed.
- Ask whether the hurdle is IRR-based or cash-on-cash-based. For illiquid operating businesses like coworking, cash-on-cash is generally more aligned with reality.
- Look at where the carry sits. If it's flowing to a sponsor entity instead of the operating team, the alignment is weaker.
- Look at the return-of-capital tier at exit. Whether the manager earns carry before or after investors get their money back is one of the most important structural decisions in a fund.
If you'd like the actual financial model, the PPM, and the full waterfall walkthrough — including the bear/base/bull scenarios with dollar figures attached that's available to accredited investors who go through our verification process — contact our Chief Growth Officer, Ben Wright at Ben@PacificWorkplaces.com to begin verification.
This article is for informational purposes only and is not an offer to sell or a solicitation of an offer to buy any security. Any offering will be made only to accredited investors pursuant to a Private Placement Memorandum under Rule 506(c) of Regulation D. Past performance is not indicative of future results. Target returns are not guarantees and actual results may differ materially